




Surveys
Logistics Performance Tracker survey
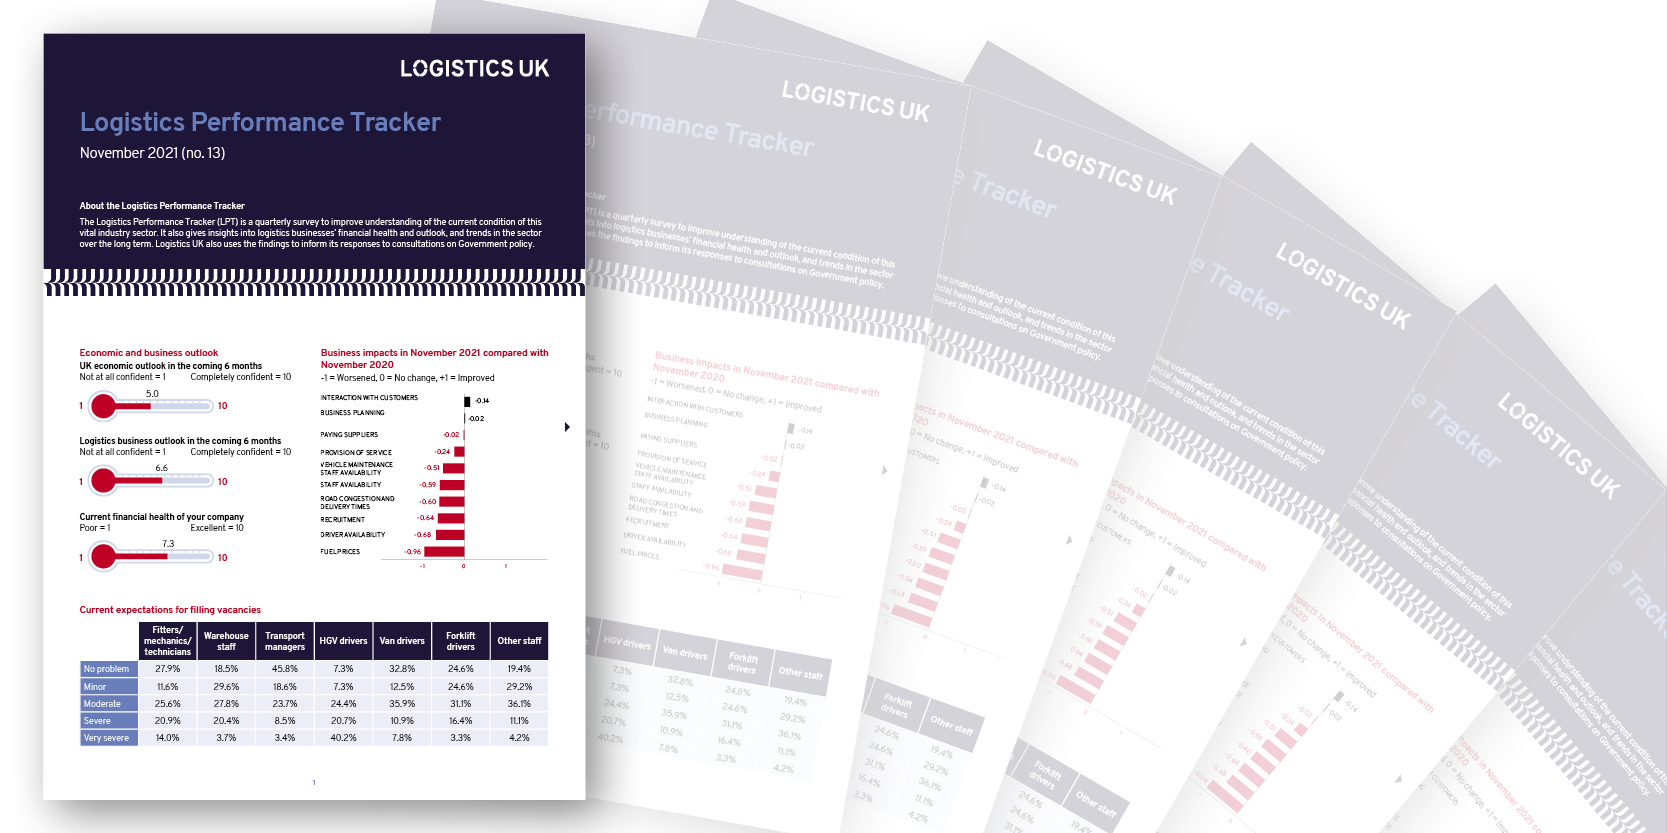
The Logistics Performance Tracker (LPT) is a quarterly survey to improve understanding of the current condition of this vital industry sector. It also gives insights into logistics businesses’ financial health and outlook, and trends in the sector over the long term.
Logistics UK also uses the findings to inform its responses to consultations on government policy. The full quarterly survey findings are sent to respondents via email.
Most recent tracker results – LPT Q3 2026 results
Headline findings include:
Business outlook and financial health
- UK GDP grew by 0.7% in Q3 2026, while transportation and storage output rose by 0.5%, reversing the 0.1% Q2 decline.
- Business outlook edged up to 6.6 out of 10, while confidence in the UK economy fell from 4.8 to 4.1 out of 10, showing firms remain more positive about their own prospects.
- Financial health rose from 7.5 to a series high of 7.8 out of 10, indicating stronger finances despite persistent costs and weaker economic confidence.
Business impacts
- Expected trends improved, but remained below neutral as worsening fuel prices and road congestion outweighed improvements elsewhere.
- Operators expect orders, freight volumes and kilometres to increase in Q4, although rising transport costs could restrict margin benefits.
- Paying suppliers remained the strongest trend, while Red Sea and Suez expectations improved, potentially reflecting greater preparedness for continuing disruption.
Supply chain issues
- Transport costs intensified as the main pressure, while border disruption, EU delivery times, paperwork and goods delays improved from Q2.
- Global shipping route disruption also worsened, showing international risk remains despite improving border and delivery measures.
- Deep Sea delays are expected to increase by 32.1%, while 65.6% expect jet fuel to increase air freight costs.
Freight rates and warehousing
- Freight rates are expected to rise across every mode, led by road freight, amid fuel, workforce and operating-cost pressure.
- Warehousing expectations rebounded, potentially reflecting business-rate pressures, although most expect no change in take-up.
- Sea-rate expectations increased only slightly, potentially because adaptation to established Red Sea disruption is limiting further effects.
Staffing and skills
- HGV drivers led modest staffing growth, with 28.4% increasing headcount and 16.8% reducing it, although unchanged staffing dominated every role.
- HGV driver sufficiency improved to 63.2%, supporting capacity, although more than one third still reported insufficient driving staff.
- Fitters, mechanics and technicians remained hardest to recruit, potentially constraining maintenance, while van driver and warehouse recruitment was easier.